
When a foreigner stays in Korea for an extended period, there often arises a need to send money back home to support family or transfer funds from an overseas account to Korea. In such cases, questions often come up, like: “Are the fees too high?”, “What exchange rate do I get?”, “Are there services other than banks that offer overseas remittance?”
Fortunately, Korea offers a variety of methods for international remittance Korea and currency exchange. From traditional bank transfers to fintech solutions and crypto-based exchange, innovative options continue to emerge. This article compiles essential information and helpful tips to ensure secure and cost-effective international transfers and currency conversions.
Traditional Bank Transfers: Reliability vs. Fees
The most familiar method is using a bank account to transfer funds overseas. By accurately inputting the recipient’s name, account number, SWIFT code (or IBAN), bank name, and branch name, you can send money either at a local bank branch or via a mobile banking app. The primary advantage is reliability. Since the transaction uses secure interbank international payment networks, the risk of funds getting lost is extremely low.
The downside is that fees can be considerable. You may end up paying a combination of domestic bank fees, intermediary bank fees, and recipient bank fees abroad. You can usually choose whether the sender or receiver covers the fees, and any exchange rate discounts can also significantly impact the total cost. In summary, traditional bank transfers are a safe and prompt option, but it may be wise to explore alternatives if minimizing fees is your priority.
Fintech Remittance Services: Hanpass, Wise, Remitalk & More
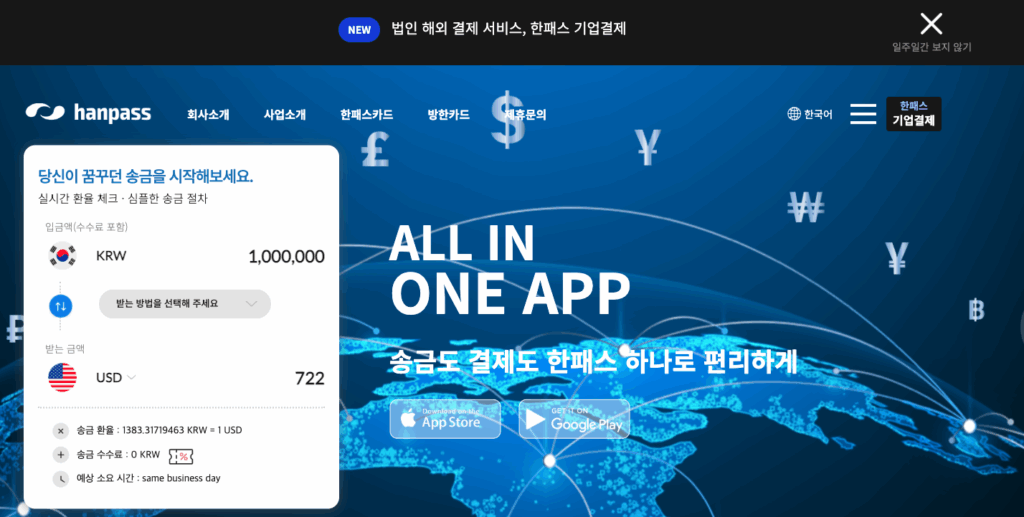
Recently, Hanpass has been gaining attention. As an innovative fintech company leading Korea’s foreign exchange market, Hanpass meets the needs of individual and corporate clients by offering various mobile-based services including international remittance, mobile payments, and PG (payment gateway) services. A key feature of Hanpass is its ability to send money to more than 200 countries, the most among domestic services. Hanpass is emerging as the standard for fast and affordable international transfers in Korea.
Launched in 2021, Hanpass’s international remittance reception service allows users to safely receive money sent from abroad. With its advanced technology, the sender only needs to know the recipient’s phone number and name, making the process much more convenient. Starting with a service launch in Australia, Hanpass plans to expand into North America, Southeast Asia, and Europe.
Additionally, fintech providers like Wise (formerly TransferWise) are transforming the paradigm of global money transfers. Rather than actually moving money internationally, these services exchange local currencies between regions, reducing fee layers and speeding up transactions. For instance, when sending money from Korea to the U.S., the sender’s KRW is matched domestically with a USD reserve Wise already holds in the U.S., and it’s paid directly from that source.
This method offers clear benefits: transparent fees and fast processing. Wise’s app and website display upfront fees, exchange rates, and estimated delivery time—sometimes even enabling same-day transfers. However, there may be limitations on the amount you can send at one time, or the account setup may be a bit tedious. Not every currency or country is supported, so it’s essential to confirm if your destination is eligible before initiating a transfer.
Using Cryptocurrency for Currency Exchange: High Risk, High Reward?
Some individuals attempt to use cryptocurrencies like Bitcoin or Ethereum to move money across borders. A typical method would involve buying crypto in Korea with KRW, transferring it to a foreign exchange, and selling it for the local currency. In theory, this approach touts reduced transaction fees, speedy delivery, and immunity to traditional exchange rate fluctuations.
In reality, however, the high volatility of cryptocurrencies can lead to significant gains or losses during the transfer process. Additionally, differing government regulations can result in legal or tax issues. In Korea, signing up for a crypto exchange requires rigorous identity verification, and anti-money laundering (AML) rules are becoming stricter. Thus, unless you are well-informed and willing to bear the risks, it’s generally not recommended to use crypto as your remittance method.
Exchange Timing and Preferential Rates: Small Tips, Big Savings
When sending money abroad, exchange is often an unavoidable step, so the exchange rate and any discounts can significantly affect your costs. Korean banks frequently offer promotional events that provide preferential exchange rates. For example, a limited-time offer could grant up to an 80% fee discount when exchanging for USD, or a 50% discount if done through internet banking. Utilizing these can cut down your fees substantially.
Because exchange rates fluctuate constantly, timing your conversion carefully may help you get a better deal. While short-term exchange rate predictions are difficult, keeping an eye on monthly trends or reacting to global events can help. While the difference may not be huge for small transfers, frequent transactions can lead to considerable cumulative savings.
Linking with Mobile Payment & Remittance Apps
Apps like Toss, Kakao Pay, and Naver Pay now offer international remittance features. After linking your Korean bank account to recharge KRW or entering overseas account information, you can easily check exchange rates and fees within the app and initiate the transfer. The main advantages are user-friendly interfaces and less cumbersome identity verification processes.
However, each app may have restrictions on transfer limits and the supported countries or currencies. It’s important to compare their fees carefully with traditional banks. Some apps also provide promotional events or reward points, which can be beneficial if used wisely.
Legal Limits and Tax Reporting
Under Korea’s Foreign Exchange Transactions Act, individuals are required to report to the National Tax Service if they send or receive more than a certain amount overseas annually. Generally, if the total exceeds USD 50,000 in a year, the bank or financial institution becomes obligated to notify authorities. You should also check tax laws in your home country and any applicable double taxation agreements.
This is particularly important when remitting living expenses to family members, as it could potentially be considered a gift, raising concerns about gift taxes. Under typical circumstances, remitting modest amounts for education or living expenses is not problematic, but repeated large transfers could attract scrutiny. If you plan on sending significant funds regularly, it’s best to consult a tax expert or banking professional to ensure compliance with legal procedures.
Conclusion: International Remittance Korea, Choose the Method That Best Suits You
For foreigners living long-term in Korea, international remittance and currency exchange are essential. With multiple options—from traditional banks, fintech apps, and cryptocurrencies to mobile payment services—it’s important to assess the pros and cons of each and pick the one that fits your needs. Your ideal choice depends on what you value most—security, low fees, speed, or convenience.
Also, don’t overlook legal limits and tax issues. Large annual sums may require bank reporting, and you could be liable for taxes either in your home country or Korea. Familiarize yourself with relevant regulations in advance and consult professionals when necessary to avoid any complications.
Ultimately, international remittance isn’t just about moving money—it’s a vital link between your life in Korea and your home country. Whether it’s sending living expenses to parents or family, or bringing overseas assets into Korea for business or property investments, having transparent and cost-effective methods helps you protect your assets and minimize currency loss or fees.
When a Transfer Stops: Tracing and Returns
As important as choosing how to send is knowing what to do when it does not arrive. International transfers pass through one or two intermediary banks, and a hold at any of them stops the money with no notification.
- Contact the sending bank, not the receiving one. A transfer that has not landed cannot be seen from the receiving side.
- Have the transfer receipt with its reference number. That number is what lets the chain of banks be queried.
- Tracing may carry a fee. Ask before requesting it.
- When funds are returned — name mismatches, closed accounts — what comes back is the amount minus fees, not the full sum.
Three causes account for most delays: a romanized name differing from the passport, a SWIFT or IBAN typo, and the receiving bank asking for extra documents. A small test transfer before the first real one filters all three at once.
Why the Amount Sent and the Amount Received Differ
Sometimes less arrives despite the fee having been paid, because three things come out and only one is quoted.
| Item | Taken by | Known in advance? |
|---|---|---|
| Sending fee | Your bank or provider | Yes — quoted at sending |
| Cable charge | Your bank | Usually quoted |
| Intermediary bank fee | Banks in the chain | No — only visible after arrival |
| Receiving bank fee | The recipient’s bank | The recipient must check |
| Exchange rate margin | Whoever converts | Calculable against the published rate |
Where an exact amount must arrive — tuition, a deposit — ask whether you can pay all charges at the sending end. It costs more and nothing is deducted along the way.
And when comparing providers, compare on “what the recipient actually gets” rather than the fee. Advertising a zero fee while taking more on the exchange rate is a common structure.
Isn’t sending via cryptocurrency cheaper?
On fees alone it can look that way, but we do not recommend it. Price movement can change the amount mid-transfer, exchanges impose their own deposit, withdrawal and verification limits, and above all it entangles foreign exchange regulation and tax questions.
In particular, refuse without exception any proposal to trade through someone else’s account or in someone else’s name. Being drawn into money laundering freezes every account you hold and brings criminal liability and residence-status consequences. Using legitimate channels is cheapest in the end.
K-Name Studio: Create your perfect Korean name based on your personality and style.
What’s My K-Beauty Personal Color?
WeBring Service : Provides personalized services to foreigners living in Korea
Exclusive offer: Introducing foreign car rental in Korea, WeBring-SoCar
- Korea Overseas Remittance Guide: Foreigner Fintech, Bank, Emigration Insurance Comparison
- Korea Overseas Remittance Guide: Fintech vs Bank Fees and Tips for Foreigners
- International Remittance Fees Decoded: Total Cost With FX Spread
- Foreign student bank account in Korea: A Complete Guide
Last updated: 22 September 2026
Rules, fees and procedures can change over time. Before an important decision, check the latest guidance from the relevant authority.
WeBring operates its own services for foreign residents in Korea. The following is a promotion for those services.
Living in Korea? You don't have to figure it out alone
Insurance, visas, jobs and hospital interpretation — WeBring supports every step of settling in Korea, in your language.